


In AI Infrastructure Race, Nokia’s Optical Bet Outpaces IBM’s Software Pivot
In AI Infrastructure Race, Nokia’s Optical Bet Outpaces IBM’s Software Pivot
Trey ThoelckeFri, September 18, 2026 at 1:05 PM UTC
0
24/7 Wall St.Quick Read -
Nokia (NOK) surged 63% year-to-date as AI and cloud revenue doubled, while IBM (IBM) dropped 20% after mainframe revenue collapsed 42%.
Nokia sells optical and IP networking hardware powering AI data centers; IBM sells the software stack, including Red Hat and watsonx, running on top.
Nokia targets 18-20% IP and Optical growth backed by a new U.S. chip fab; IBM cut full-year guidance to 4-5%, banking on deferred Q2 deals closing.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
Nokia (NYSE:NOK) and IBM (NYSE:IBM) have delivered similar five-year returns of 92.7% and 83.9%, respectively. Year to date, the paths diverged sharply. Nokia is up 62.8% after a Q2 beat-and-raise. IBM is down 19.7% after a rare EPS miss.
AI Orders Lift Nokia. Mainframe Timing Sinks IBM.
Nokia's July report showed AI and cloud customer revenue more than doubling, up 105% in constant currency, with Q2 order intake of €2.8 billion in that segment. Optical Networks grew 20% and IP Networks 16%. CEO Justin Hotard said, "Demand remains strong, while supply continues to be the main industry constraint."
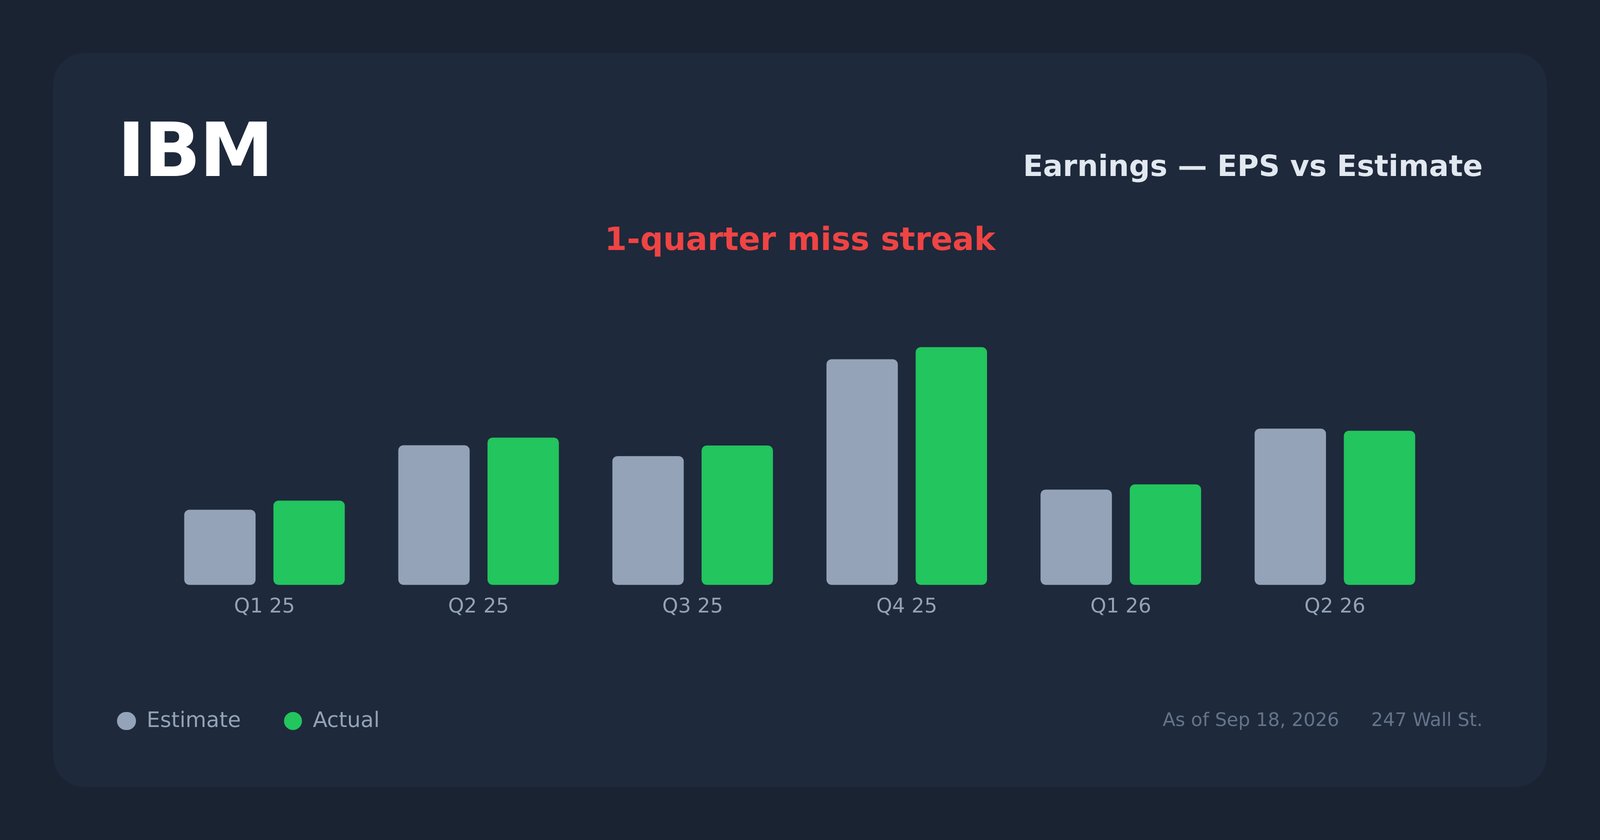
IBM went the other way. Q2 revenue grew just 1.1%, and operating EPS of $2.93 missed the $2.97 consensus. Software rose 5.1%, with Red Hat up 11%, but Infrastructure fell 7.4% as IBM Z mainframe revenue collapsed 42% in a late-cycle trough. CEO Arvind Krishna conceded the quarter "fell short of expectations," blaming deferred capex deals rather than lost demand.
Learn 13 Major Retirement Mistakes and Ways To Avoid Them
One investment mistake could create big risks for your retirement. Many investors make the same critical errors: being too conservative, making big bets on “sure things,” or paying excessive fees. Any of those blunders can endanger your hard-earned savings.
Now you can learn the mistakes even experienced investors make (and ways you can sidestep them before it’s too late) with this new guide: 13 Retirement Mistakes and How to Avoid Them from Fisher Investments. Access your complimentary copy here(sponsor)
IBM Earnings Explorer — 24/7 Wall St.Plumbing Versus What Runs on It
The two reside in AI infrastructure at different layers. Nokia sells physical plumbing: optical transport (fiber gear moving data between and inside data centers) and IP routing (switches directing traffic). Its Infinera acquisition and planned purchase of NXP's fab in Chandler, Arizona, for indium phosphide production are bets on owning that supply chain. IBM sells what runs on top: Red Hat OpenShift, watsonx orchestration, HashiCorp, Confluent, and mainframes that process over 70% of the world's transaction value. (The suppliers benefiting from that buildout, from power to cooling to networking, are the subject of a free report we put together.)
Advertisement
Lens
Nokia
Core Bet
Optical and IP for AI data centers
Hybrid cloud software and mainframe
Q2 Growth Engine
AI & Cloud sales +105%
Data software +18%
Weak Spot
Fixed Networks −3%
IBM Z −42%
Revenue Base
Carrier and hyperscaler capex cycles
~80% recurring software
A Patent Portfolio IBM Cannot Match
Nokia also runs a technology licensing business through Technology Standards, which grew 15% in the quarter. That royalty stream on cellular standards has no IBM analog in networking, and it cushions Nokia when carrier spending sags. A majority of Nokia's sales are billed in dollars despite its Finnish base, so a stronger euro would compress reported profits for U.S. ADR holders.
Next Test: Deferred Deals and Supply Ramps
IBM claims delayed Q2 transactions were "deferral and not destruction" and lowered its full-year constant-currency revenue growth guidance to 4%–5%. Nokia expects combined IP and Optical revenue to grow 18%–20% and aims for indium phosphide fab volume production by Q4 2026.
What the Market Is Paying For
At $10.60 per share, Nokia trades at a forward P/E near 22, pricing in a durable AI infrastructure supercycle and successful U.S. manufacturing pivot. IBM, at $237.75, carries a forward P/E near 18, a 2.8% yield, and 31 consecutive years of dividend increases. One is priced as a cyclical growth story that is delivering. The other is priced as a compounder working through an execution stumble and an active securities fraud inquiry.
NOK Analyst Ratings — 24/7 Wall St.
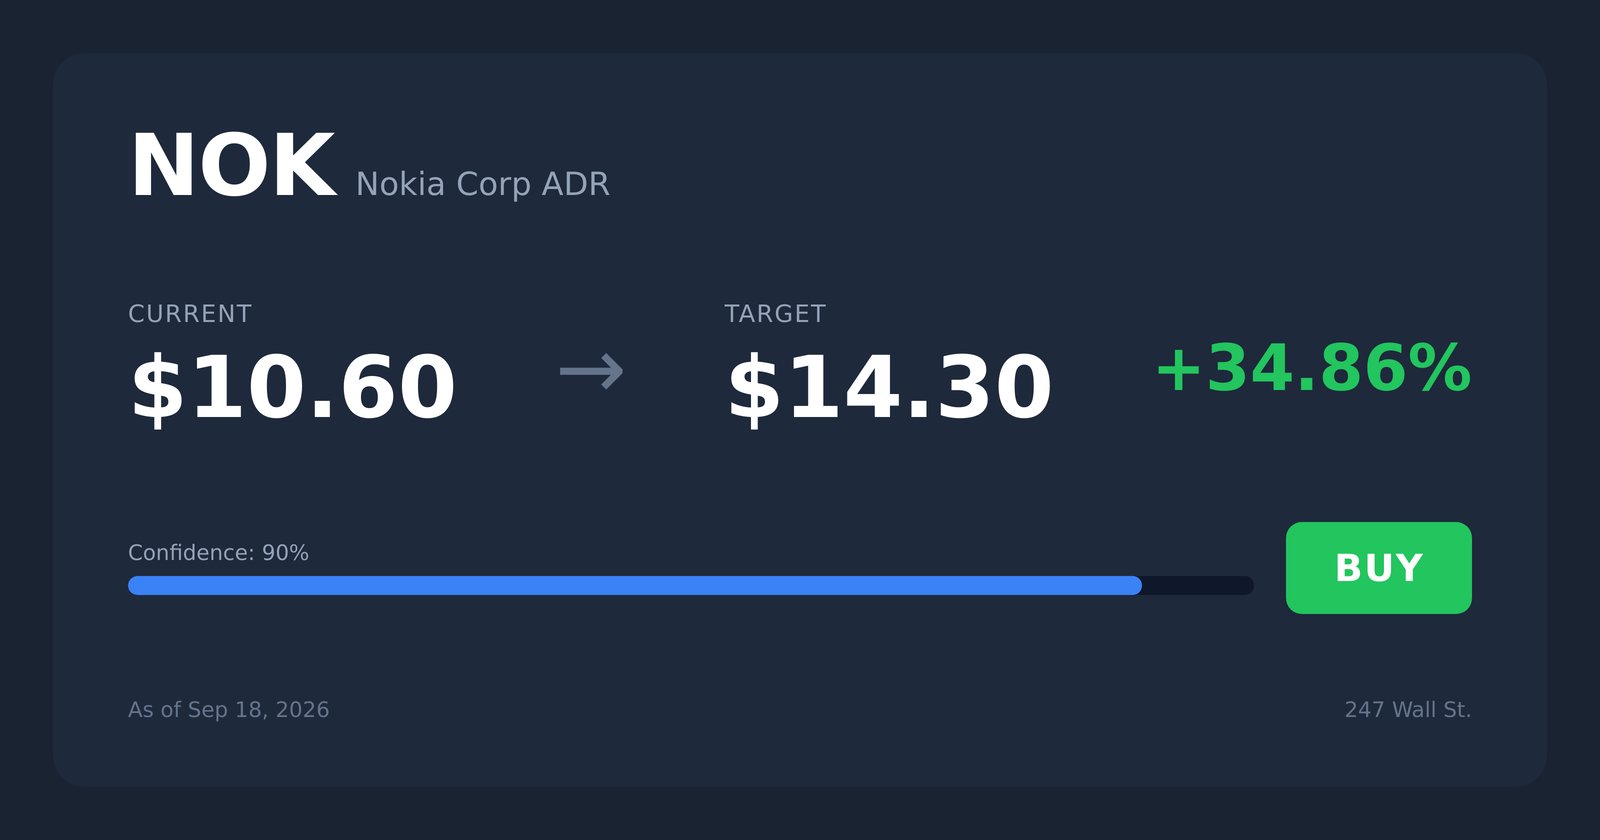
NOK Price Target — 24/7 Wall St.
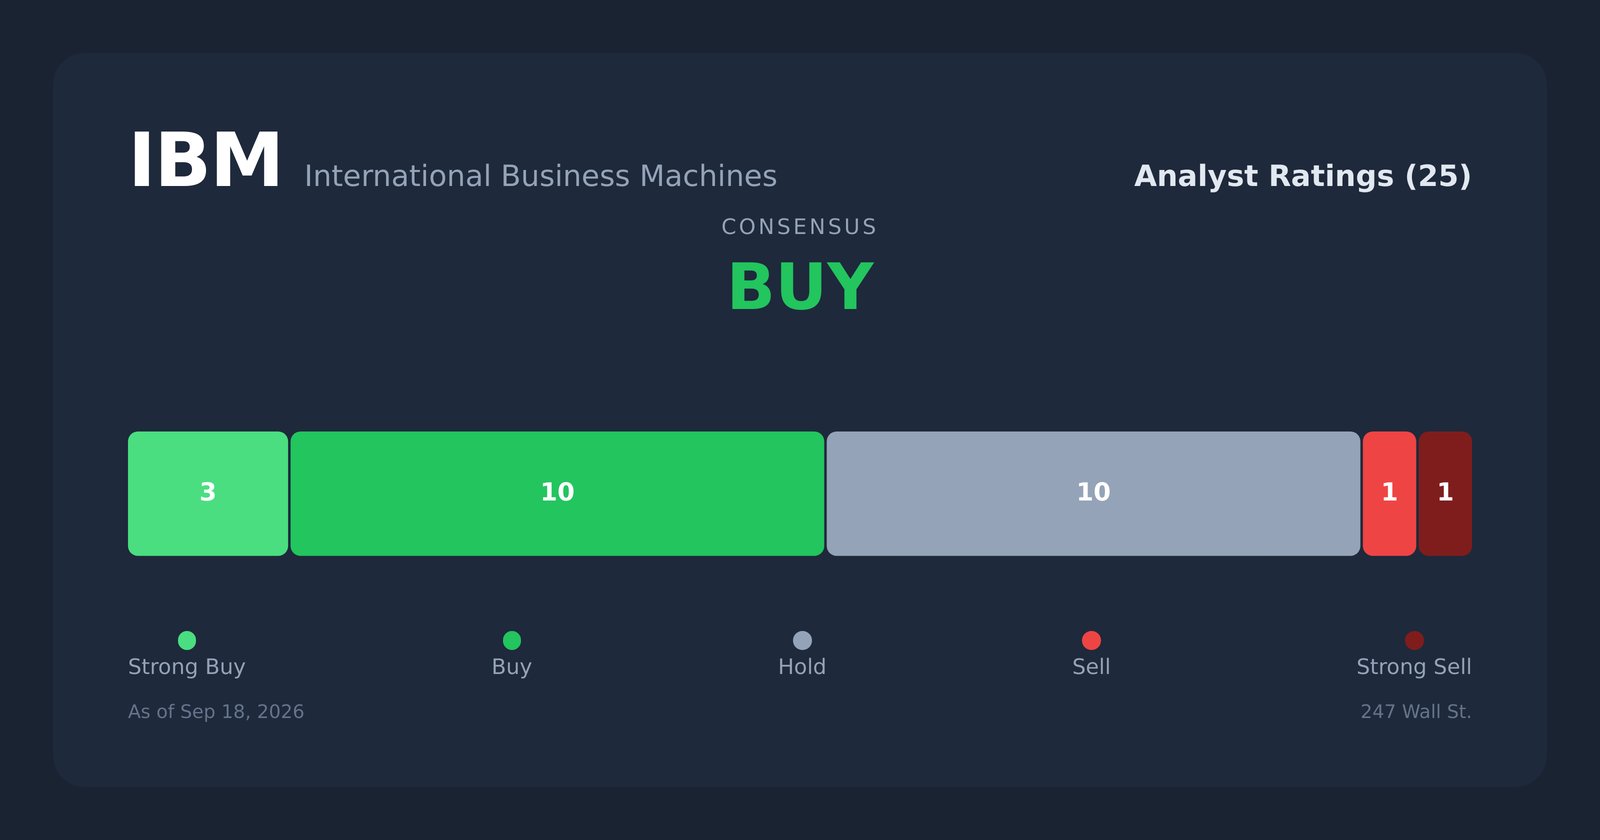
IBM Analyst Ratings — 24/7 Wall St.
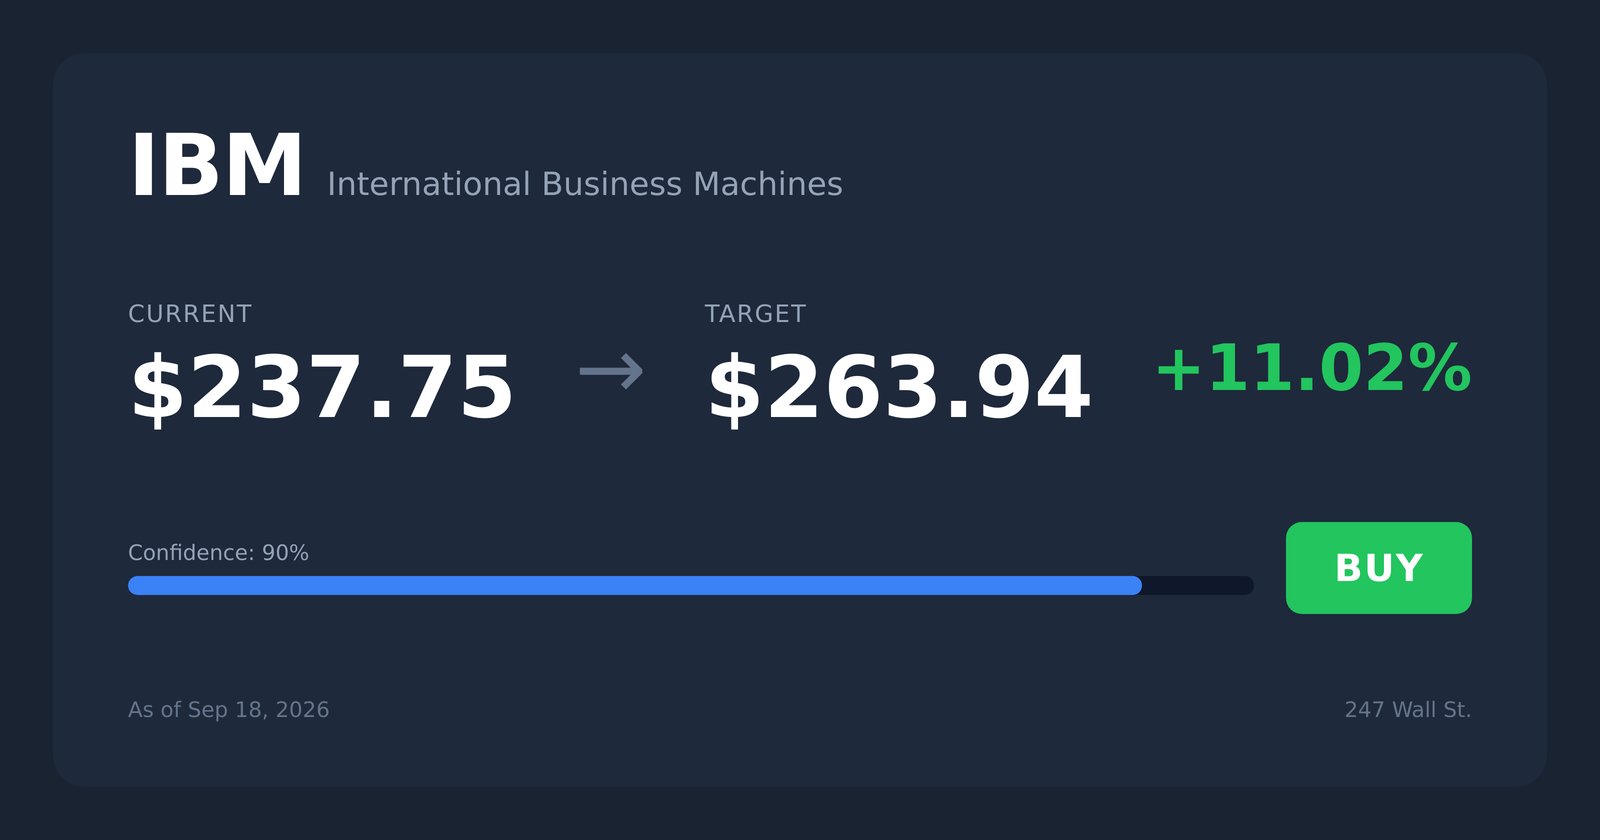
IBM Price Target — 24/7 Wall St.Help Avoid These 13 Retirement Mistakes Before They Derail Your Future
One investment mistake could create big risks for your retirement. Many investors make the same critical errors: being too conservative, making big bets on “sure things,” or paying excessive fees. Any of those blunders can endanger your hard-earned savings.
Now you can learn the mistakes even experienced investors make (and ways you can sidestep them before it’s too late) with this new guide: 13 Retirement Mistakes and How to Avoid Them from Fisher Investments. (sponsor)
Contact editorial@247wallst.com for any questions or corrections.
Source: “AOL Money”
